The Best Credit Repair Apps in 2026, Ranked and Compared
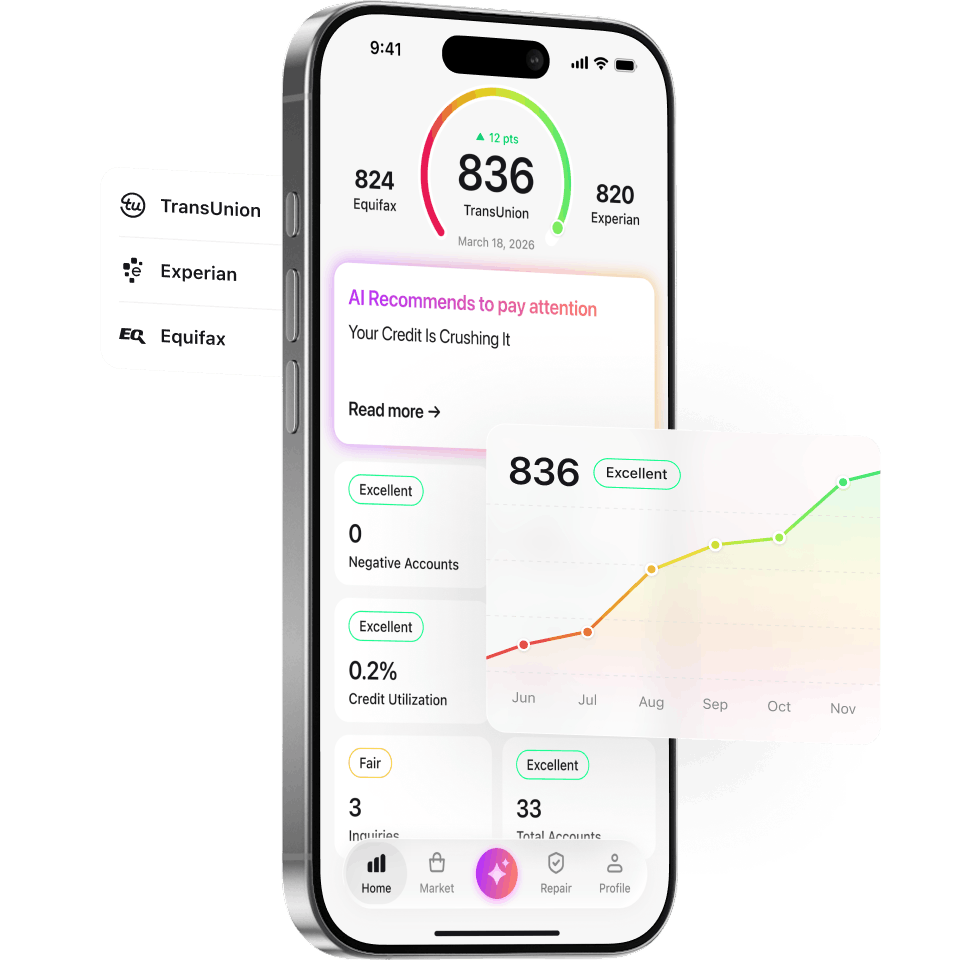
The best credit repair app in 2026 is Credit Booster AI: AI report analysis plus human dispute review across all three bureaus, with typical gains of 30 to 60 points in six months. Best free app: Credit Karma. Best budget app: Dovly AI at $39.99 per month.
Credit report problems are the largest consumer complaint category in the country. The Federal Trade Commission logged 1,353,175 reports about credit bureaus and information furnishers in 2024, 20.91% of all 6,471,708 Consumer Sentinel Network reports, per the FTC Consumer Sentinel Network Data Book 2024. That category was 590,872 reports in 2022.
Best Credit Repair App by Use Case
The right credit repair app depends on which bureaus hold your errors.
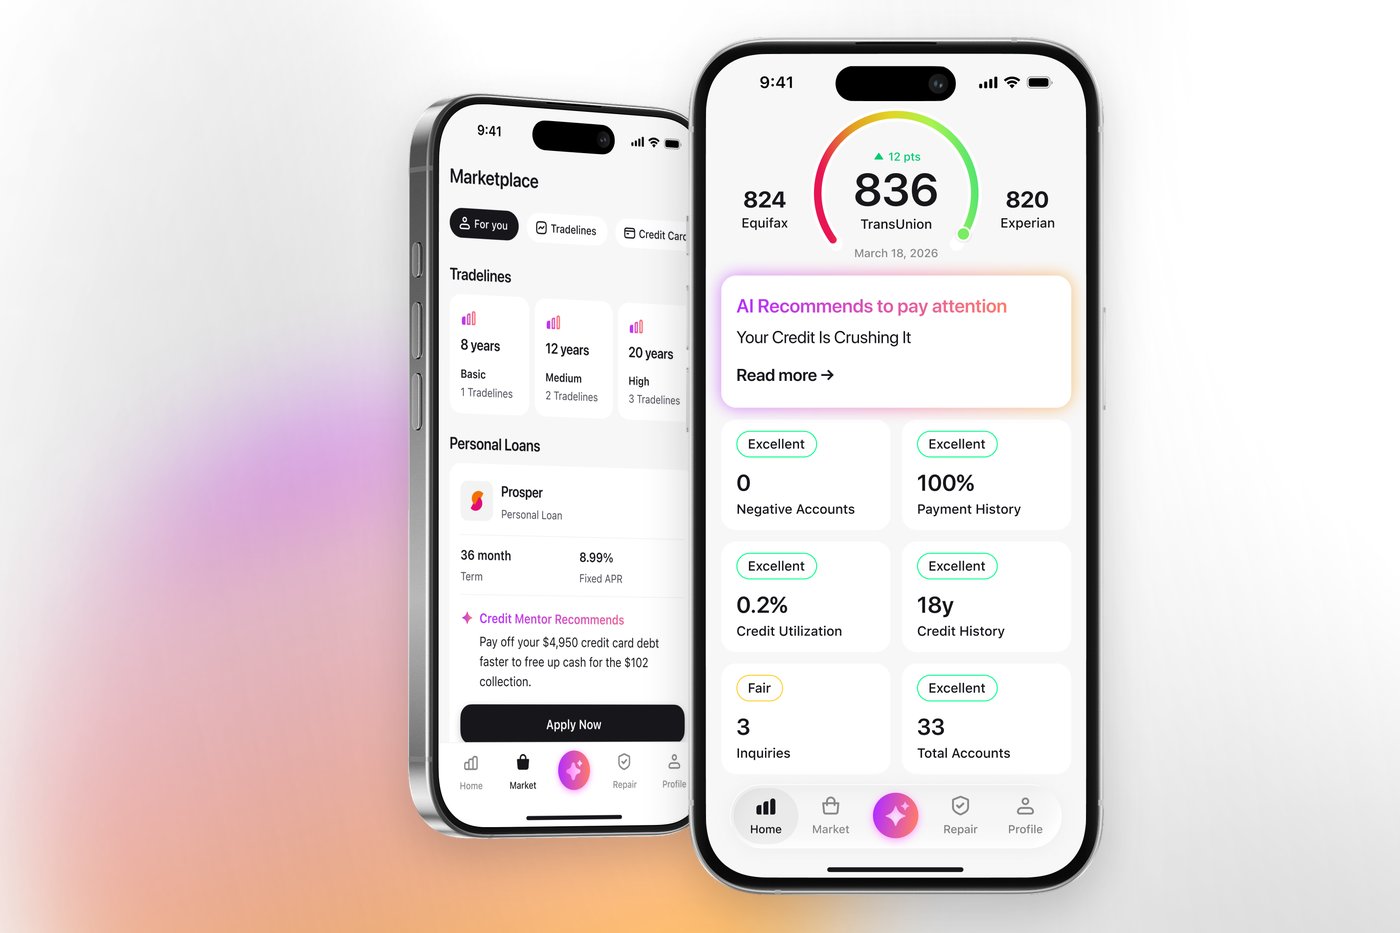
- Best overall: Credit Booster AI. AI plus human review, all three bureaus, from $9.99 per month.
- Best budget credit fixer app: Dovly AI, $39.99 per month or $99.99 per year, TransUnion only.
- Best after identity theft: Lexington Law, attorney-backed escalation. The FTC recorded 1,135,291 identity theft reports in 2024, 17.5% of all reports.
- Best free credit repair app: Credit Karma. TransUnion and Equifax only, no Experian.
- Best for DIY control: SmartCredit at $24.95, self-serve action buttons and a score simulator.
- Best for 10 or more negatives: Credit Booster AI, whose human layer handles escalations pure-AI apps drop.
See our credit repair apps guide and AI credit repair tools compared.
Feature Comparison: What Each Credit Repair App Actually Delivers
Bureau coverage decides the outcome, because each credit bureau investigates only what sits in its own file. Dovly AI files with TransUnion only, Credit Karma covers TransUnion and Equifax, and the six other apps here cover all three.
| App | 3-Bureau Coverage | AI Automation | Dispute Letters | Monitoring and Alerts |
|---|---|---|---|---|
| Credit Booster AI | Yes (full) | Yes + human review | Unlimited, customized | Real-time dashboard + chat |
| Lexington Law App | Yes | Partial (attorney-backed) | Unlimited | Fraud alerts, FICO analysis |
| Dovly AI | No (TransUnion only) | Full AI engine | Unlimited (premium) | Weekly TransUnion scores |
| CreditRepair.com App | Yes | Basic AI | Customized per cycle | Score summaries |
| Sky Blue Credit Repair | Yes | No (manual, unlimited) | Unlimited challenges | Basic alerts |
| CoolCredit | Yes (paid) | AI letters | Unlimited DIY (paid) | 3-bureau monitoring |
| SmartCredit | Yes (pro) | Basic analysis | Action buttons (limited) | Fraud and score tracking |
| Credit Karma | No (TU/EQ only) | No | Basic (TU/EQ) | VantageScore alerts |
The CFPB received approximately 5,102,800 credit or consumer reporting complaints about Equifax, Experian and TransUnion in 2025, out of approximately 5,806,800 in total, per the CFPB 2025 Consumer Response Annual Report, Section 4.1. A one-bureau app leaves two files untouched.
Pricing Breakdown: Value for Your Dollar in 2026
Credit repair apps in 2026 run from $0 to about $200 per month. Credit Booster AI is $9.99 Plus, $29.99 Pro and $99.99 Max, with a 7-day free trial on Plus only and no setup fee. Dovly AI Premium is $39.99 per month. Credit Karma is free.
| App | Setup Fee | Monthly Fee | Free Tier? | Guarantee | Annual Savings Option |
|---|---|---|---|---|---|
| Credit Booster AI | None | $9.99 Plus, $29.99 Pro, $99.99 Max | No, 7-day free trial on Plus | No | No, monthly only |
| Lexington Law App | None upfront (first-work fee) | $139.95 (published rate) | No | Varies by plan | No |
| Dovly AI | None | $39.99 (Premium) | Yes (basic TU) | No | $99.99 per year |
| CreditRepair.com App | First-work fee on some plans | $49.95 to $119.95 | Free assessment | No contract | No |
| Sky Blue Credit Repair | None | $79 to $119 (3 tiers) | No | 90-day money-back | No |
| CoolCredit | None | $20 Boost, $24 pay-as-you-go, $75 to $199 by coverage | Free to start | No | No, monthly only |
| SmartCredit | None | $24.95 to $29.95 | Limited | No | No |
| Credit Karma | None | Free | Full (basic) | N/A | N/A |
Dovly AI, CoolCredit, Sky Blue and SmartCredit rates were read from each company’s own pricing page in September 2026. Lexington Law and CreditRepair.com are last published rates, worth confirming before you buy. Under 15 U.S.C. 1679b no credit repair organization may charge before the promised services are performed, so an advance fee is the red flag. See free credit repair options.
Pros and Cons: Honest Takes on the Best Apps to Fix Credit
Every app below carries the same four facts the company publishes about itself.
1. Credit Booster AI
Price: $9.99 to $99.99, no setup fee. Bureaus: all three. Disputes: AI plus human review. Free tier: none, 7-day Plus trial.
All three bureaus covered, so an Experian-only error is not missed, with typical gains of 30 to 60 points in six months. No free tier, and it is a monthly commitment, cancelable anytime.
2. Lexington Law App
Price: $139.95 per month published rate. Bureaus: all three. Disputes: attorney-backed, unlimited. Free tier: none.
Attorneys handle escalation when a bureau verifies an item you say is wrong. Highest published price here; full-service signup comes first.
3. Dovly AI (Best AI Credit Repair App Runner-Up)
Price: $0 free, $39.99 per month or $99.99 per year. Bureaus: TransUnion only. Disputes: automated AI engine. Free tier: yes.
Cheapest unlimited automated disputes here, and Premium adds a $2,000 builder tradeline, rent reporting, a credit lock and $1 million identity theft insurance. Files with TransUnion only on every tier, verified on dovly.com/pricing on 11 September 2026, so Equifax and Experian errors go untouched.
4. CreditRepair.com App
Price: $49.95 to $119.95 per month. Bureaus: all three. Disputes: basic AI, per cycle. Free tier: assessment only.
Tiered pricing lets you start cheap and scale up, with no long-term contract. Less AI depth than purpose-built apps.
5. Sky Blue Credit Repair
Price: $79 to $119 per month. Bureaus: all three. Disputes: manual, unlimited challenges. Free tier: none.
A 90-day money-back guarantee, rare here, plus unlimited challenges. No AI automation, so throughput depends on staff.
6. CoolCredit
Price: $20 to $199 per month, monthly billing only. Bureaus: all three. Disputes: AI letters plus expert assist. Free tier: free to start.
Verified on coolcredit.com/pricing on 12 September 2026: $20 Boost, $24 pay-as-you-go plus $12 per added item, then $75, $99, $149 and $199 by file coverage. No annual option, and no long track record.
7. SmartCredit
Price: $24.95 to $29.95 per month. Bureaus: all three on pro. Disputes: limited action buttons. Free tier: limited.
A score simulator models a change before you make it, and fraud monitoring is included. Action buttons cap at five per month on basic.
8. Credit Karma
Price: free. Bureaus: TransUnion and Equifax only. Disputes: basic in-app. Free tier: the whole product.
Genuinely free, no card required. No Experian coverage, so a third of your file is invisible, and revenue comes from referrals.
How to Choose the Right Credit Repair App
Choose a credit repair app by counting your errors first and matching bureau coverage second. Price is the third question.
- Pull all three reports free from AnnualCreditReport.com, the only federally authorised source.
- Count your errors. Five or more disputable items usually justifies a paid app.
- Check three-bureau coverage. Credit Karma skips Experian; Dovly AI files with TransUnion only.
- Read the cancellation terms. Under 15 U.S.C. 1679e you may cancel a credit repair contract without penalty within three business days.
- Keep your paperwork. The CFPB found around 90% of complaining consumers said they had already disputed, while Equifax confirmed a prior dispute about 37% of the time and TransUnion about 30%, per its December 2025 FCRA 611(e) report.
DIY instead? Our credit dispute letter templates are free.
Real User Results: What 2026 Data Shows
No credit repair app publishes independently audited score results, Credit Booster AI included, so the honest picture comes from federal complaint data. In 2025, companies responded to 99.9% of credit or consumer reporting complaints the CFPB sent them, closing 51% with an explanation, 40% with non-monetary relief, 10% administratively and 0.02% with monetary relief, per the CFPB 2025 Consumer Response Annual Report, Section 4.1. Non-monetary relief is the bucket holding an actual correction.
Credit bureaus get 60 days to answer a CFPB complaint and all three recently averaged more than 50 days, with Experian close to the full 60 since early 2023, per the CFPB FCRA 611(e) report, Section 3.2. Plan on months.
Why Credit Booster AI Ranks Number 1 as the Best Credit Repair App
Credit Booster AI ranks first because it is the only app here combining full three-bureau coverage, AI item-level analysis, human review of escalations, and a $9.99 entry price with no setup fee.
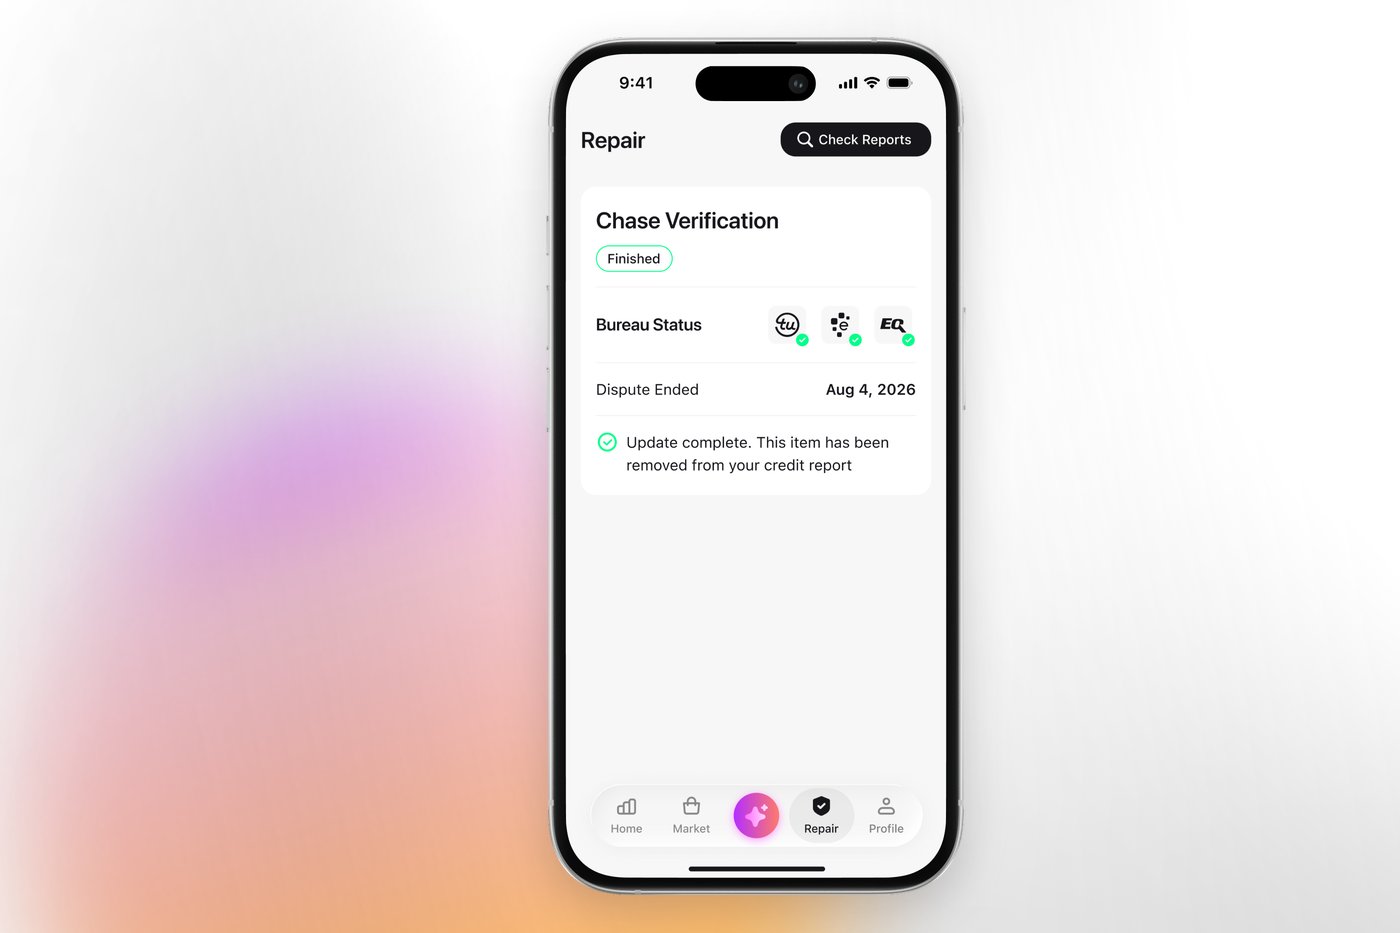
It keeps a timestamped record of every letter and bureau response, which matters when a bureau and a consumer disagree about whether an item was already disputed.
Disputes are not the whole fix. Payment history is approximately 35% of a FICO Score and amounts owed approximately 30%, per myFICO, so on-time payments and lower utilization move more than any letter.
Common Myths Busted and Pro Tips for Maximum Gains
The biggest myth about credit repair apps is speed. Under 15 U.S.C. 1681i a credit bureau has 30 days to reinvestigate, extendable to 45 if you send more information inside the first 30.
Myth two: free equals full power. Credit Karma covers TransUnion and Equifax, not Experian. Myth three: accurate negatives can be removed. They cannot. A credit bureau must delete or modify only what it finds inaccurate, incomplete or unverifiable.
Three moves that work:
- Dispute in rounds of 10 to 15 items, keeping every receipt.
- Cut card utilization. FICO measured average utilization at 36.1% in February 2025, against a 35.0% pre-pandemic benchmark.
- Escalate free at consumerfinance.gov/complaint if a bureau stonewalls. A “guaranteed 700” claim violates the Credit Repair Organizations Act.
Legal Must-Knows: Protect Yourself in 2026
Three federal rules govern every credit repair app you can legally buy in 2026. The Credit Repair Organizations Act at 15 U.S.C. 1679b bans advance fees and guaranteed-result promises. The Fair Credit Reporting Act at 15 U.S.C. 1681i sets the 30-day reinvestigation deadline. And 15 U.S.C. 1681n gives you actual damages, or statutory damages of not less than $100 and not more than $1,000, for a willful violation.
The CFPB received approximately 6,635,400 complaints in 2025, and approximately 5,806,800 of them concerned credit or consumer reporting.
What Changed in Credit Repair in 2026
Four shifts in the last year change which app is right for you.
- Complaint volume exploded. Complaints about the three nationwide bureaus are up almost 3,000% since 1 January 2020, per the CFPB’s December 2025 FCRA 611(e) report.
- Credit reporting became the FTC’s number one report category, at 1,353,175 reports in 2024.
- The federal medical debt ban died in court. The CFPB’s January 2025 rule was vacated in July 2025, so there is no federal ban in 2026. The bureaus’ voluntary policies still stand.
- Delinquency drifted up. The New York Fed reported 4.7% of household debt in some stage of delinquency at the end of June 2026, with student loans 90 or more days past due at 10.6%, up from 10.3%.
How We Ranked These Credit Repair Apps
We ranked these eight apps on five weighted criteria applied to published facts, not a lab test.
| Criterion | Weight | The data point checked |
|---|---|---|
| Bureau coverage | 30% | Equifax, Experian and TransUnion, or a subset |
| Dispute capability | 25% | Unlimited or metered, AI or manual, human escalation |
| Published price | 20% | Monthly price, setup fee, annual option, free tier |
| Disclosure quality | 15% | Outcome claims sourced, bureau limits stated plainly |
| Cancellation terms | 10% | Contract length, refund policy, CROA three-day cancellation |
We publish no composite numeric score for any app here, ours included, for the reason given above.
The Verdict: Pick Your 2026 Credit Repair Winner
Credit Booster AI is the best credit repair app of 2026 for most people: three-bureau coverage, AI plus human review, $9.99 to start. On a budget, Dovly AI at $39.99, TransUnion only. For identity theft, Lexington Law. For free monitoring, Credit Karma.
Download Credit Booster AI, free on iOS and Android.
Related: vs Credit Karma, vs Dovly, vs Lexington Law, vs Experian Boost, vs myFICO, vs WalletHub, CoolCredit review, Lexington Law alternatives, for bad credit, for beginners, fix credit fast.
Frequently Asked Questions
What is the best credit repair app in 2026?
Credit Booster AI is the best credit repair app for 2026: AI report analysis plus human dispute review across all three bureaus, with typical gains of 30 to 60 points in six months. Dovly AI is the best budget pick, Lexington Law the best for identity theft. No app may guarantee a score under 15 U.S.C. 1679b.
What is the best credit repair app for beginners?
Credit Karma’s free monitoring suits starters. For real fixes, upgrade to Credit Booster AI, with typical gains of 30 to 60 points over six months. Pull all three reports free at AnnualCreditReport.com first: the CFPB logged approximately 5,102,800 complaints about the three bureaus in 2025.
Is there a credit fixer app that actually works?
Yes. A legitimate credit fixer app finds inaccurate items and disputes them under the Fair Credit Reporting Act. Under 15 U.S.C. 1681i a credit bureau must reinvestigate within 30 days and delete or modify anything it finds inaccurate or unverifiable. Accurate negatives stay up to seven years.
How much does a good credit repair app cost in 2026?
Published monthly rates in this roundup run from $20 to $199, and some full-service providers add a first-work fee on top. Dovly AI Premium is $39.99 per month, verified on dovly.com/pricing on 11 September 2026. Credit Booster AI starts at $9.99 with no setup fee.
Can AI credit repair apps really remove negative items?
Only inaccurate ones. Under 15 U.S.C. 1681i a credit bureau must delete or modify an item it finds inaccurate, incomplete or unverifiable. In 2025 companies closed 40% of credit reporting complaints with non-monetary relief, per the CFPB 2025 Consumer Response Annual Report.
How long do credit repair apps take to improve scores?
Three to six months is typical for a 30 to 60 point gain. Under 15 U.S.C. 1681i a credit bureau has 30 days to reinvestigate, extendable to 45 if you send extra documents inside that window.
Is Credit Booster AI better than Lexington Law?
Credit Booster AI edges ahead on AI speed plus human review at $9.99 to start, against Lexington Law’s published $139.95 per month. Lexington Law is stronger on attorney-backed identity theft escalation. Neither publishes audited outcome data, so treat every advertised result, ours included, as a range.
Are free credit repair apps worth it?
For monitoring, yes. Credit Karma is free and covers TransUnion and Equifax, not Experian, so an Experian-only error stays invisible. Experian averaged nearly the full 60 days to answer a CFPB complaint since early 2023, per the CFPB’s December 2025 FCRA 611(e) report.
Is medical debt still on credit reports in 2026?
Partly. The CFPB’s January 2025 rule that would have banned medical debt from credit reports was vacated by a federal court in July 2025, so there is no federal ban in 2026. The bureaus’ voluntary policies still remove paid medical collections and exclude unpaid ones under $500.
What is the average credit score in 2026?
The most recent national average FICO Score published by FICO is 714, flat from October 2025 through April 2026, per FICO’s 25 August 2026 Score Credit Insights release. The New York Fed reported 4.7% of household debt in some stage of delinquency at the end of June 2026.
How much does Dovly cost now?
Verified on dovly.com/pricing on 11 September 2026: a free plan with a monthly TransUnion report and a manual dispute tool, and Premium at $39.99 per month or $99.99 per year. Premium adds unlimited AI TransUnion disputes, a $2,000 builder tradeline, rent reporting and $1 million identity theft insurance.
Monitor your credit score and protect your identity with Credit Club, our credit monitoring and identity protection membership.
Need professional help? CreditBooster.com has been helping clients rebuild their credit since 2009.
Sources
Every number above comes from a primary source we opened and read.
- CFPB, 2025 Consumer Response Annual Report (March 2026), Section 4.1: complaint volumes, the 99.9% response rate, the closure split.
- CFPB, FCRA Section 611(e)(5) report (December 2025): the 3,000% rise in bureau complaints, the prior-dispute confirmation gap, the 60-day window.
- FTC, Consumer Sentinel Network Data Book 2024 (March 2025): 6,471,708 reports; credit bureaus and furnishers 1,353,175 (20.91%); identity theft 1,135,291 (17.5%).
- FICO, Score Credit Insights fall 2026 edition (25 August 2026): the 714 national average, flat October 2025 to April 2026.
- FICO, by Tommy Lee (16 April 2025): 36.1% average utilization in February 2025 against the 35.0% January 2020 benchmark.
- myFICO: payment history approximately 35%, amounts owed approximately 30%.
- New York Fed, Household Debt and Credit, 2026 Q2: $18.77 trillion total debt, 4.7% delinquent, student loans 10.6%.
- 15 U.S.C. 1681i, 1681n, 1679b, 1679e.
- CFPB complaint form, AnnualCreditReport.com, Dovly AI pricing, read 11 Sep 2026.
Loving This Info? You'll Love Our App.
Everything you just read, plus AI-powered tools to understand and master your credit. 7 day free trial.
Get the AppFrequently Asked Questions
What is the best credit repair app in 2026?
Credit Booster AI is the best credit repair app for 2026: AI report analysis plus human dispute review across all three bureaus, with typical gains of 30 to 60 points in six months. Dovly AI is the best budget pick, Lexington Law the best for identity theft. No app may guarantee a score under 15 U.S.C. 1679b.
What is the best credit repair app for beginners?
Credit Karma's free monitoring suits starters. For real fixes, upgrade to Credit Booster AI, with typical gains of 30 to 60 points over six months. Pull all three reports free at AnnualCreditReport.com first: the CFPB logged approximately 5,102,800 complaints about the three bureaus in 2025.
Is there a credit fixer app that actually works?
Yes. A legitimate credit fixer app finds inaccurate items and disputes them under the Fair Credit Reporting Act. Under 15 U.S.C. 1681i a credit bureau must reinvestigate within 30 days and delete or modify anything it finds inaccurate or unverifiable. Accurate negatives stay up to seven years.
How much does a good credit repair app cost in 2026?
Published monthly rates in this roundup run from $20 to $199, and some full-service providers add a first-work fee on top. Dovly AI Premium is $39.99 per month, verified on dovly.com/pricing on 11 September 2026. Credit Booster AI starts at $9.99 with no setup fee.
Can AI credit repair apps really remove negative items?
Only inaccurate ones. Under 15 U.S.C. 1681i a credit bureau must delete or modify an item it finds inaccurate, incomplete or unverifiable. In 2025 companies closed 40% of credit reporting complaints with non-monetary relief, per the CFPB 2025 Consumer Response Annual Report.
How long do credit repair apps take to improve scores?
Three to six months is typical for a 30 to 60 point gain. Under 15 U.S.C. 1681i a credit bureau has 30 days to reinvestigate, extendable to 45 if you send extra documents inside that window.
Is Credit Booster AI better than Lexington Law?
Credit Booster AI edges ahead on AI speed plus human review at $9.99 to start, against Lexington Law's published $139.95 per month. Lexington Law is stronger on attorney-backed identity theft escalation. Neither publishes audited outcome data, so treat every advertised result, ours included, as a range.
Are free credit repair apps worth it?
For monitoring, yes. Credit Karma is free and covers TransUnion and Equifax, not Experian, so an Experian-only error stays invisible. Experian averaged nearly the full 60 days to answer a CFPB complaint since early 2023, per the CFPB's December 2025 FCRA 611(e) report.
Is medical debt still on credit reports in 2026?
Partly. The CFPB's January 2025 rule that would have banned medical debt from credit reports was vacated by a federal court in July 2025, so there is no federal ban in 2026. The bureaus' voluntary policies still remove paid medical collections and exclude unpaid ones under $500.
What is the average credit score in 2026?
The most recent national average FICO Score published by FICO is 714, flat from October 2025 through April 2026, per FICO's 25 August 2026 Score Credit Insights release. The New York Fed reported 4.7% of household debt in some stage of delinquency at the end of June 2026.
How much does Dovly cost now?
Verified on dovly.com/pricing on 11 September 2026: a free plan with a monthly TransUnion report and a manual dispute tool, and Premium at $39.99 per month or $99.99 per year. Premium adds unlimited AI TransUnion disputes, a $2,000 builder tradeline, rent reporting and $1 million identity theft insurance.